Does Homeowners Insurance Cover Roof Replacement in Florence, SC?
Homeowners in Florence, SC, have good reason to wonder whether their insurance policy will pay for a full roof replacement. This article covers when it does, when it does not, and what helps a claim succeed. Working with a trusted roofing contractor in Florence, SC, makes the process smoother.
When Does Homeowners Insurance Cover Roof Replacement?
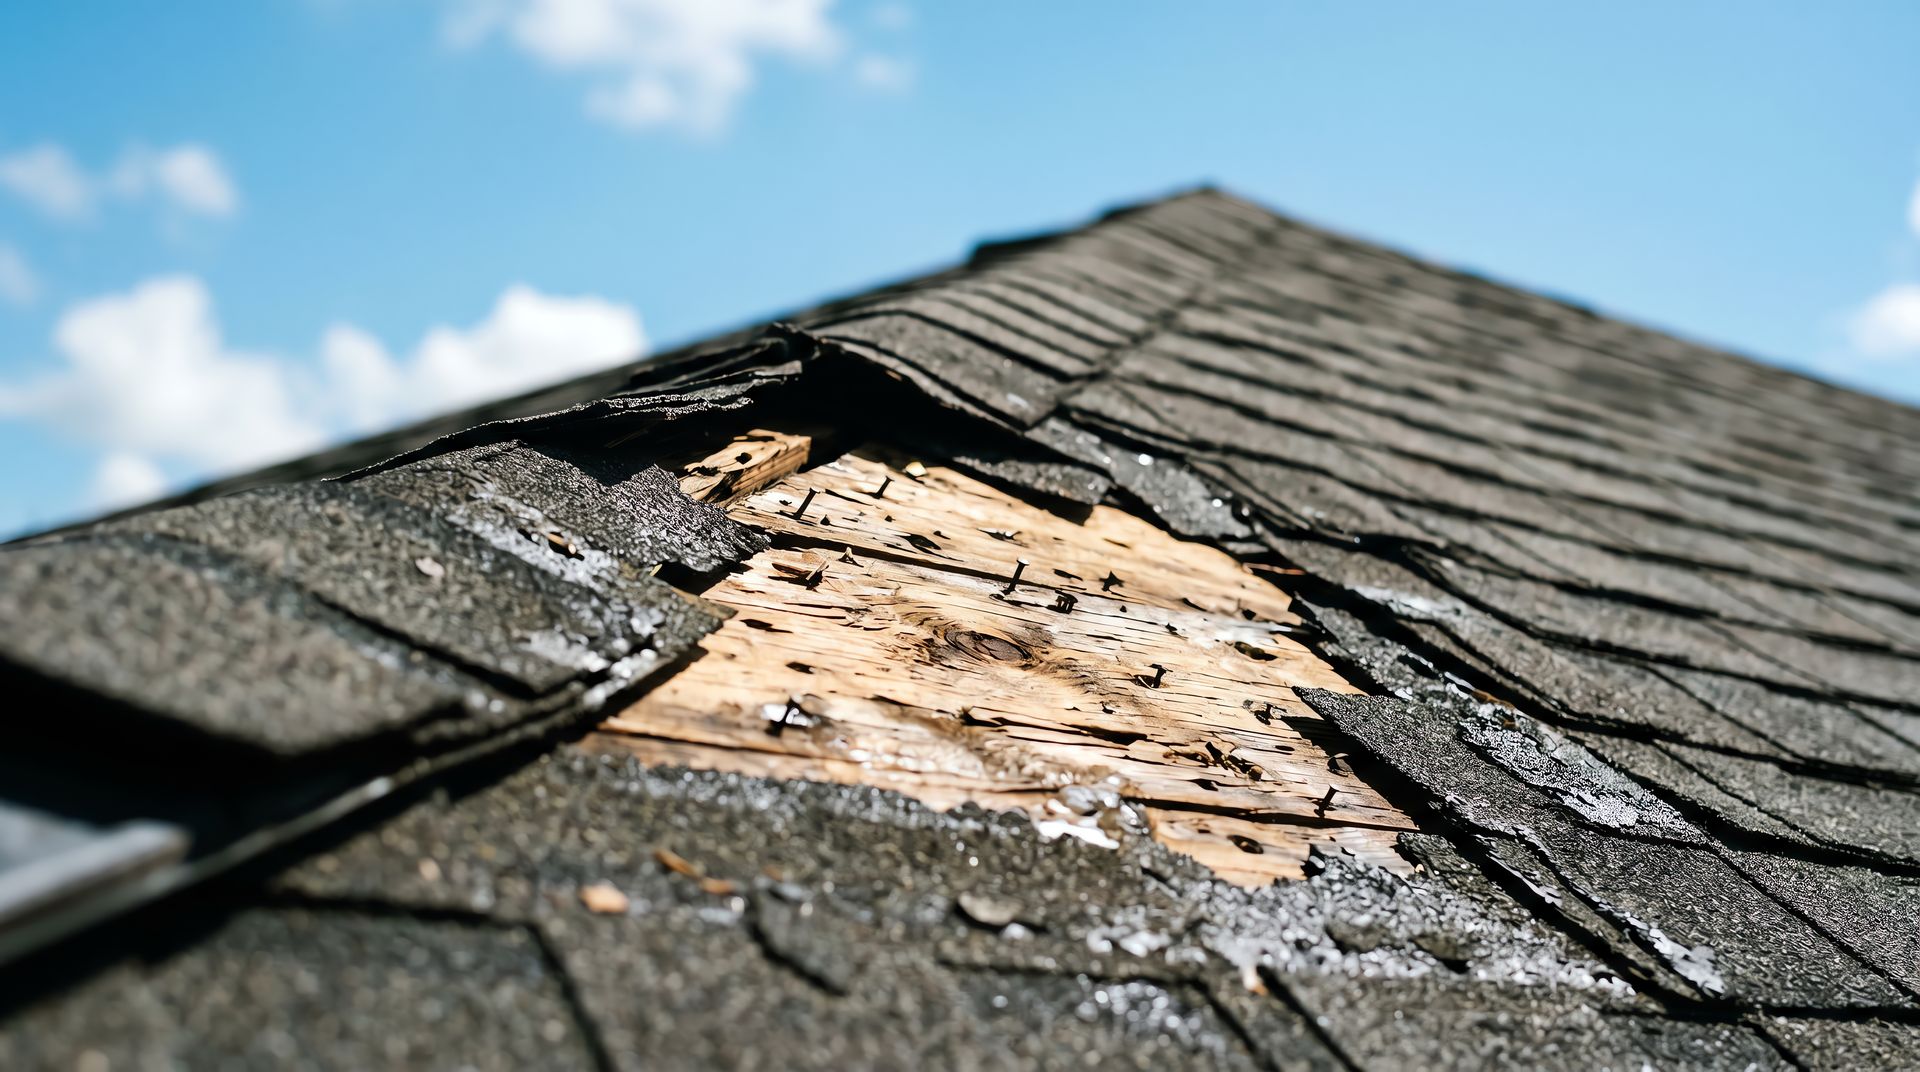
Most standard homeowners insurance covers sudden, accidental roof damage. Because the roof is part of the dwelling, if a covered event damages it badly enough, your insurer may pay for a full replacement rather than just a patch.
Covered causes typically include wind and hail from thunderstorms, tropical storms, and hurricanes. If matching shingles are no longer available or repair is impractical, the claim can become a full replacement. Fallen trees and limbs are covered whether from your property or a neighbor's. Fire and lightning damage generally results in full replacement coverage.
Florence County sits in the Pee Dee region, where severe weather is a regular reality. Thunderstorms roll through from spring into early fall, bringing hail, lightning, and straight-line winds. Consulting a roofing contractor in Florence, SC, after any significant storm tells you where you stand before calling your insurer.
What Does Homeowners Insurance Typically Not Cover?
Insurance will generally not pay for a roof that simply wore out; wear and tear is a standard exclusion. Gradual leaks are also excluded, since water seeping in over months points to deterioration. Neglect can void coverage if earlier damage went unrepaired. Flood damage is never covered under a standard home policy and requires a separate flood policy.
Hail claims have been climbing across South Carolina, and Florence is no exception. However, if your roof is older than 15 years, expect carriers to scrutinize it closely. A qualified roofing contractor in Florence, SC, can assess whether your roof's condition could create problems before you ever file a claim.
Replacement Cost vs. Actual Cash Value
How your policy pays out matters as much as whether it covers the event. Some policies insure the house at replacement cost value but pay the roof at actual cash value, which factors in depreciation. On an 18-year-old architectural shingle roof, that settlement can be a fraction of the actual cost.
Florence homeowners should also watch deductibles. Many policies carry a separate wind and hail deductible set as a percentage of dwelling coverage, commonly 1 to 5 percent, rather than a flat dollar amount.
What Should You Do Before Filing a Claim?
Act quickly but carefully. Here are the key steps Florence homeowners typically follow after storm damage:
- Document everything as soon as it is safe. Photograph all visible damage from ground level before anyone walks on the roof.
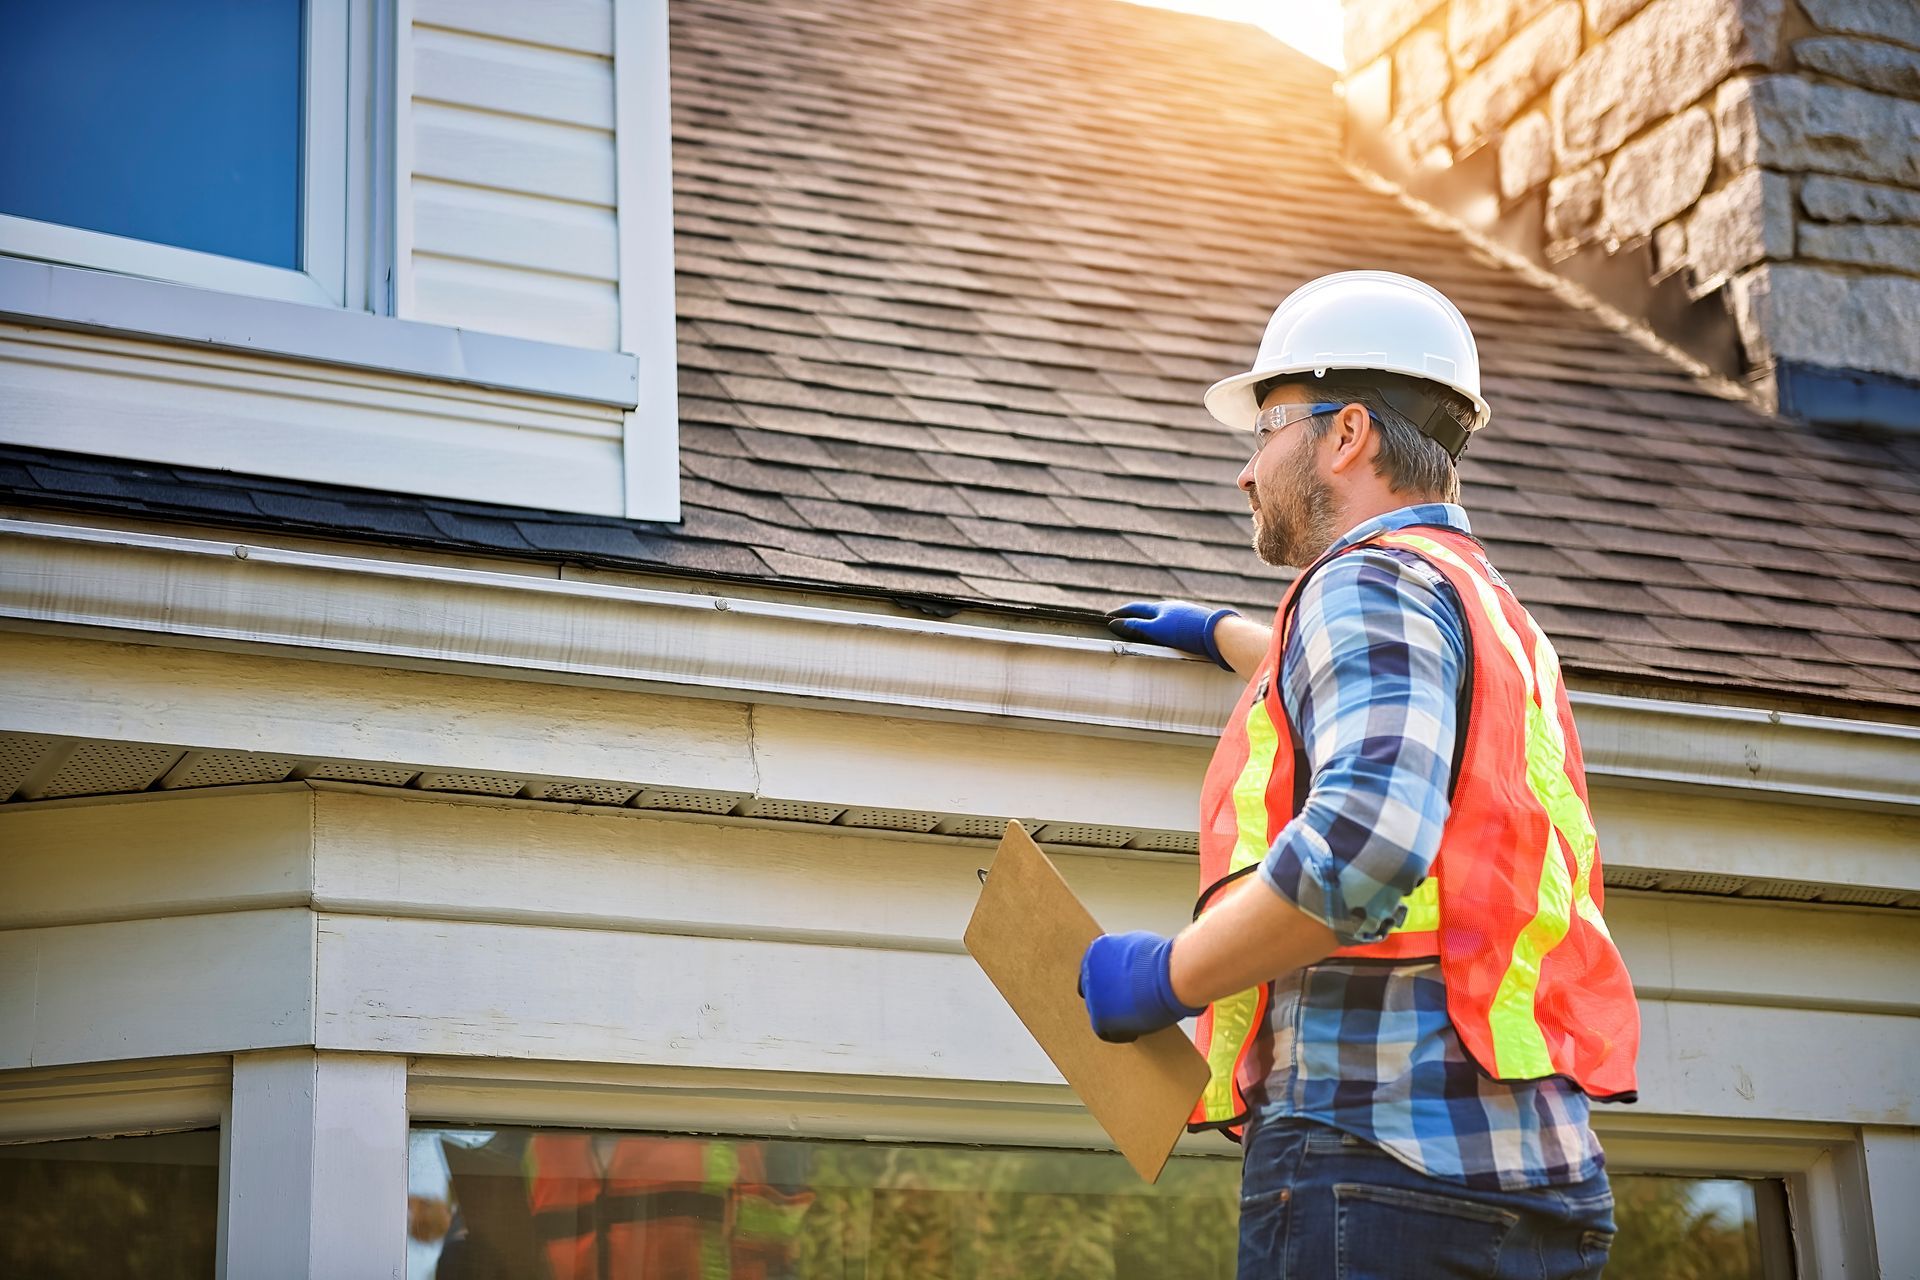
- Call a licensed roofing contractor in Florence, SC, to conduct a professional inspection. A contractor can identify damage not visible from the ground, including fractured shingles and compromised flashing.
- Request a written damage report and itemized estimate. Insurers typically require this documentation to process a claim.
- Contact your insurance company promptly. Most policies have time limits on how long after an event you can file.
- Be present when the adjuster visits, and share the contractor's written report so nothing gets overlooked.
Working with an experienced
roofing contractor serving Florence, SC, early in the process helps ensure the full scope of damage is documented properly.
Florence-Specific Factors to Keep in Mind
The Pee Dee climate creates specific challenges. Florence County homes face spring thunderstorms, summer tropical moisture, and the outer bands of Atlantic hurricanes tracking inland from the coast. Most standard South Carolina policies include windstorm coverage, though some properties may require a separate wind and hail policy through the South Carolina Wind and Hail Underwriting Association. An experienced roofing contractor in Florence, SC, can help you identify vulnerabilities before severe weather tests them.
Frequently Asked Questions About Roof Insurance Claims in Florence, SC
Does Insurance Cover Roof Replacement Due to Age Alone?
No. Age-related wear and tear is almost universally excluded. Coverage applies to sudden, accidental damage from a covered event. Regular maintenance and timely repairs protect your ability to file a claim after a storm.
Will a Roofing Contractor Help with My Insurance Claim?
Yes. A licensed contractor can inspect your roof, document damage with photos and a written report, and provide an itemized estimate that supports a more complete claim outcome.
How Long Do I Have to File a Roof Damage Claim in South Carolina?
Most policies specify a time window after the damage-causing event. Check your policy documents and contact your insurer as soon as damage is discovered to avoid a denial based on late reporting.
What if My Insurer Only Wants to Pay for Repairs Instead of a Full Replacement?
If a contractor determines a full replacement is more appropriate, their written assessment can be submitted to support your position. You may also request a re-inspection or engage a public adjuster to independently review the claim.
Get a Roof Inspection Before Your Next Claim
A documented history of maintenance and prompt repairs can demonstrate to an insurer that damage was caused by a specific event rather than ongoing neglect. If you have recently experienced a storm and suspect damage, reaching out to a roofing contractor in Florence, SC, is a smart first step.
DeFee Roofing Inc. has been serving the Pee Dee area, including Florence, SC, for nearly two decades. Fully licensed and insured, the team can inspect your roof, provide a written damage report, and help you understand your options before you file a claim. Call
(843) 229-2171 or
contact us online to request your free estimate today.
How to Handle a Storm Damage Roofing Claim in Sumter County, SC: A Step-by-Step Guide for Homeowners